

What looks like a positive guidance for Q3, -5% YoY revenue growth against -25% of Q2, doesn’t excite me much.
Playing a bit with the numbers, my take away is that the improvement is driven by:
SpoiledChild weighting more in the revenue mix (above 40%) as IlMakiage revenue drops
SpoiledChild not affected as bad as IlMakiage by the algo dislocation
Management investing more in SpoiledChild Customer acquisition in 2026 H2 vs 2025 H2 (remember that most of the Customer acquisition for Oddity happens in Q1 normally)
Methodiq doing better than expected, ramping up its business
This is why I say so, in order.
SpoiledChild had a good quarter and a strong year to date, 2026 overall, and it is on track to grow at least 35 percent this year and approach $350 million of net revenue in 2026
$350 million of net revenue is 43% of 2025 ODD total revenue, which so start to play with IlMakiage 1:1 (IlMakiage rev is declining in FY26).
We believe SpoiledChild is being impacted by the algorithm dislocation issues IL MAKIAGE is facing, but to a lesser degree, and this has allowed us to continue scaling the brand
So it makes sense they are pushing the gas pedal a bit more than usual in H2.
Management is guiding for “net revenue will decline approximately 5 percent year-over-year”
Management has shared in the past that repeat sales is around 70% of total sales, so we can assume that il Makiage is declining 20% to 30% YoY (few new customers) in Q3 while SpoiledChild partially compensate it with its 35% growth. What is missing to get to -5% is made by Methodiq, which the management said doing better than SpoiledChild in year 1 after launch, which according to my estimation bring us to Methodiq sales in 2026 H2 around 15 $M per quarter. This is all incremental on 2025, as Methodiq was launched at the end of the year.
Confirming this scenario, there are both IlMakiage and SpoileChild web visits, which just keep declining both YoY and sequentially, which suggest that customer acquisition is not solved yet.
Oddity products are great
My take away here is that Oddity is becoming better to farming current user base, especially with SpoileChild, and also the products are great and Customers love it. Here the reviews growth from 2025 to date (please note that the numbers in the graph are not 100% accurate because I normally collect the data at the time of earnings, anyway data are good enough for the purpose):
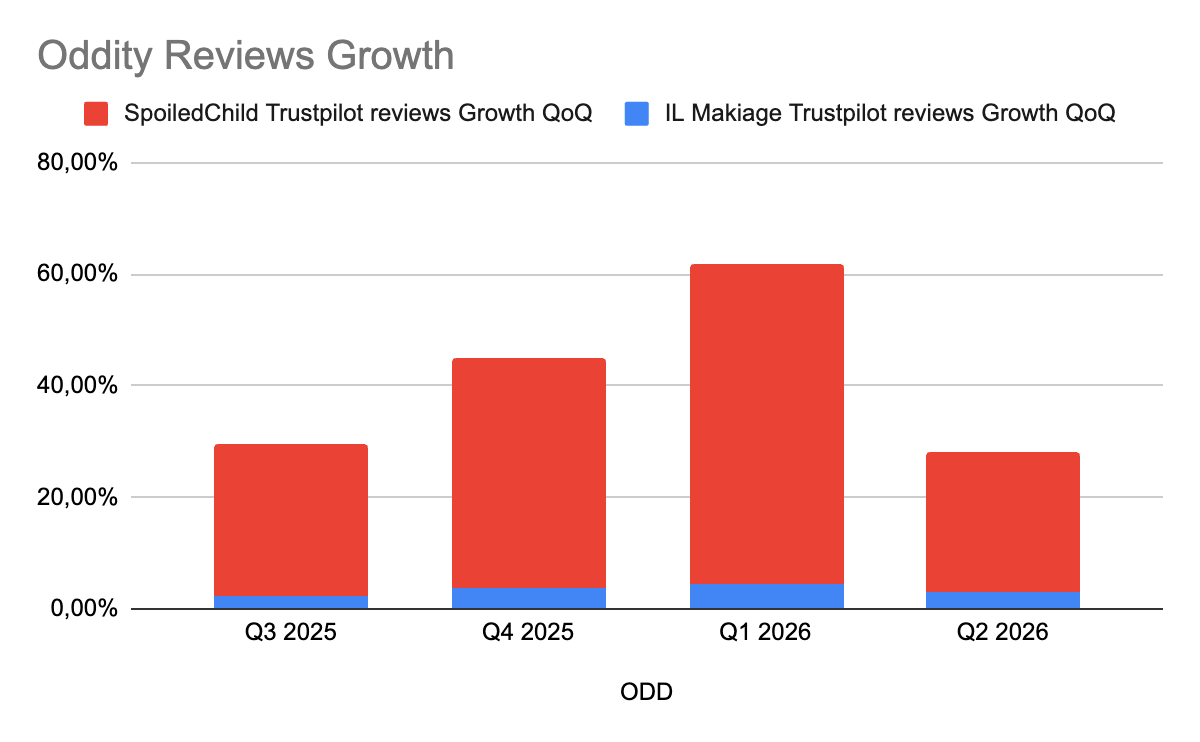
Also, at the same the rating from 2025 to 2026 improved for all brands, now sitting average to 4,5 over 5, a great score for this kind of consumer goods company.
This numbers indeed supports what management is saying.
SpoiledChild continues to deliver very strong customer service cohorts metrics like AOV and repeated scale. 12 months net revenue repeat rates for the brand are well in excess of 100 percent today.
Oddity going physical
Yes, first of all, we learned a lot. The past few months were very intense in terms of media buying world. I must say that we thought that we know a lot, but now after those months, we are very deep in the details and learning every day better how those algorithms work. We increased our efforts both to fix the problem, but to make the business more resilient moving forward, including more distribution and more channels. We have nothing yet to announce, but once we have, we will. We believe that the key of the business is data, and in order to continue to have that ability, we need to remain focused. A big portion of the business must remain D2C. That is our strength, and we need to continue to work with those ad partners. By the way, the way that we work now with the ad partner and their commitment and like it is unbelievable
This comment to me suggests that Oddity is going either to distribute their products through digital or phsycal retailers (E.g. Amazon or Sephora) or is opening their own physical stores.
I would bet on the second.
Oddity main focus should remain D2C of course, which is the whole thesis, but I think owning a few selected stores in strategic locations (New York, London, Milan, ...) will be a net positive strategy.
On the negative of course there is the cost of operating the stores, on the positive there is:
improved brand awareness
physical distribution platform to acquire new customers, so diversification from Meta channel (which otherwise would likely remain the biggest D2C acquisition channel)
At the end of the day, if we assume that a new customer acquired through a store will then keep buying online on the D2C channel (which is reasonable to be assumed because it is convenient), the physical store operation cost can be considered as CAC.
Once CAC from the stores < than CAC from META, Oddity wins.
I firmly believe that, as long as stores remain limited to a few hundreds globally, this may be a winning strategy.
This is of course my speculation, there isn’t anything confirmed by Oddity, but I bet Oddity is thinking about doing this, let’s not forget that they already have a limited physical presence (<5% of revenue is coming from stores).
As always, here is the “Deep Dive To Date” (DDTD), that is how the stock is performing since my initial deep dive on the July 16th 2024, when the price was $44.24.
-58% DDTDIf you want access to:
My portfolio
all my trades in real time
my price targets and how I calculate them
Business Ontology content
My price targets will be shared in the Telegram Group and explained on my Youtube channel.
I share my thoughts on X.
Please note that:
I can be and will be (hopefully not often) WRONG. This is just my personal strategy—NOT FINANCIAL ADVICE. I don’t know your financial or life situation well enough to give any recommendations. Please do your own due diligence and research. Don’t be LAZY.
Be the architect of your own destiny.
Ciao
Lorenzo