

Elon once said that in tech the winner is not the company that is ahead at any point in time; the one who moves faster wins
If it is true that share price follows free cash flow, eventually, and it is true, to be successful you need to predict where the free cash flow is headed, because once the direction is clear to the herd it is too late to get alpha from an investment. Well, I believe that, in tech, free cash flow follows speed of execution, which is the ultimate leading indicator.
Now, to Duolingo. Long story short, I don’t think they are moving fast enough.
First of all, I haven’t just sold Duolingo, I fully ported it into HIMS. I want to point it out because in a concentrated portfolio like the one I am managing, the total return highly depends (even more than a diversified portfolio) on how you allocate your capital over the few positions.
So the reason I made this move is that I judged HIMS at this point had a much higher asymmetry than Duol. And Duol was anyway a small position, so at a certain point either I doubled down or I allocated that money differently, as for me it does not make sense to hold a few percent position.
This quote is from Q2:
…this work is making Duolingo a better product. We believe that’s driving increased word of mouth and improving our top-of-funnel growth
This is a good summary of Duolingo’s management strategy for the last 9 months. They think that by making the product better, they will improve their top of funnel meaningfully. I doubt it.
As I explained in my article Duolingo: The Owl Has a Distribution Problem published on May 12, 2026, Duolingo reached peak search interest (measured with Google trends) last year around the Dead Duo campaign. That campaign was genius: impossible to ignore, and very Duolingo. But that is exactly the point. You cannot schedule virality every quarter.
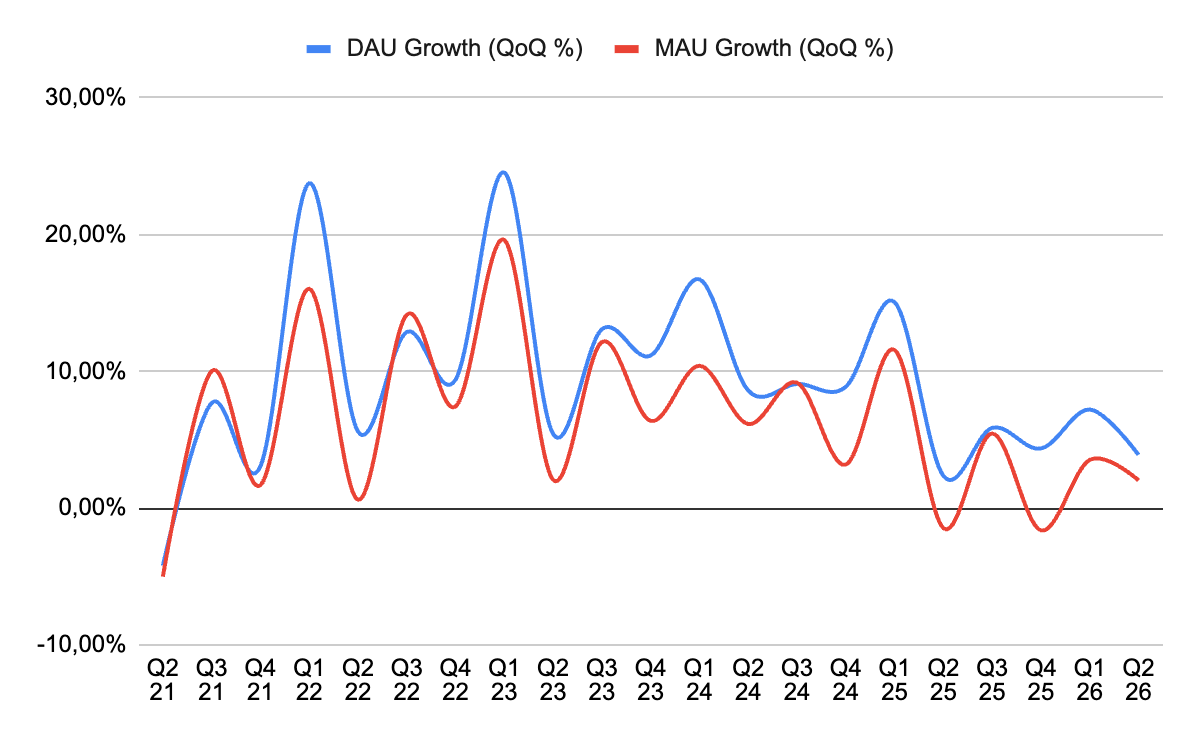
After Dead Duo, interest did not keep compounding. It got worse, and MaU and DaU growth together went down to the lowest point.
Unless your thesis is that in the same period of time the product got worse, this proves that the top of funnel at this stage of the company’s maturity is uncorrelated (or not meaningfully correlated) with any product’s marginal improvements. Which signals that most likely the management strategy is not going to work out.
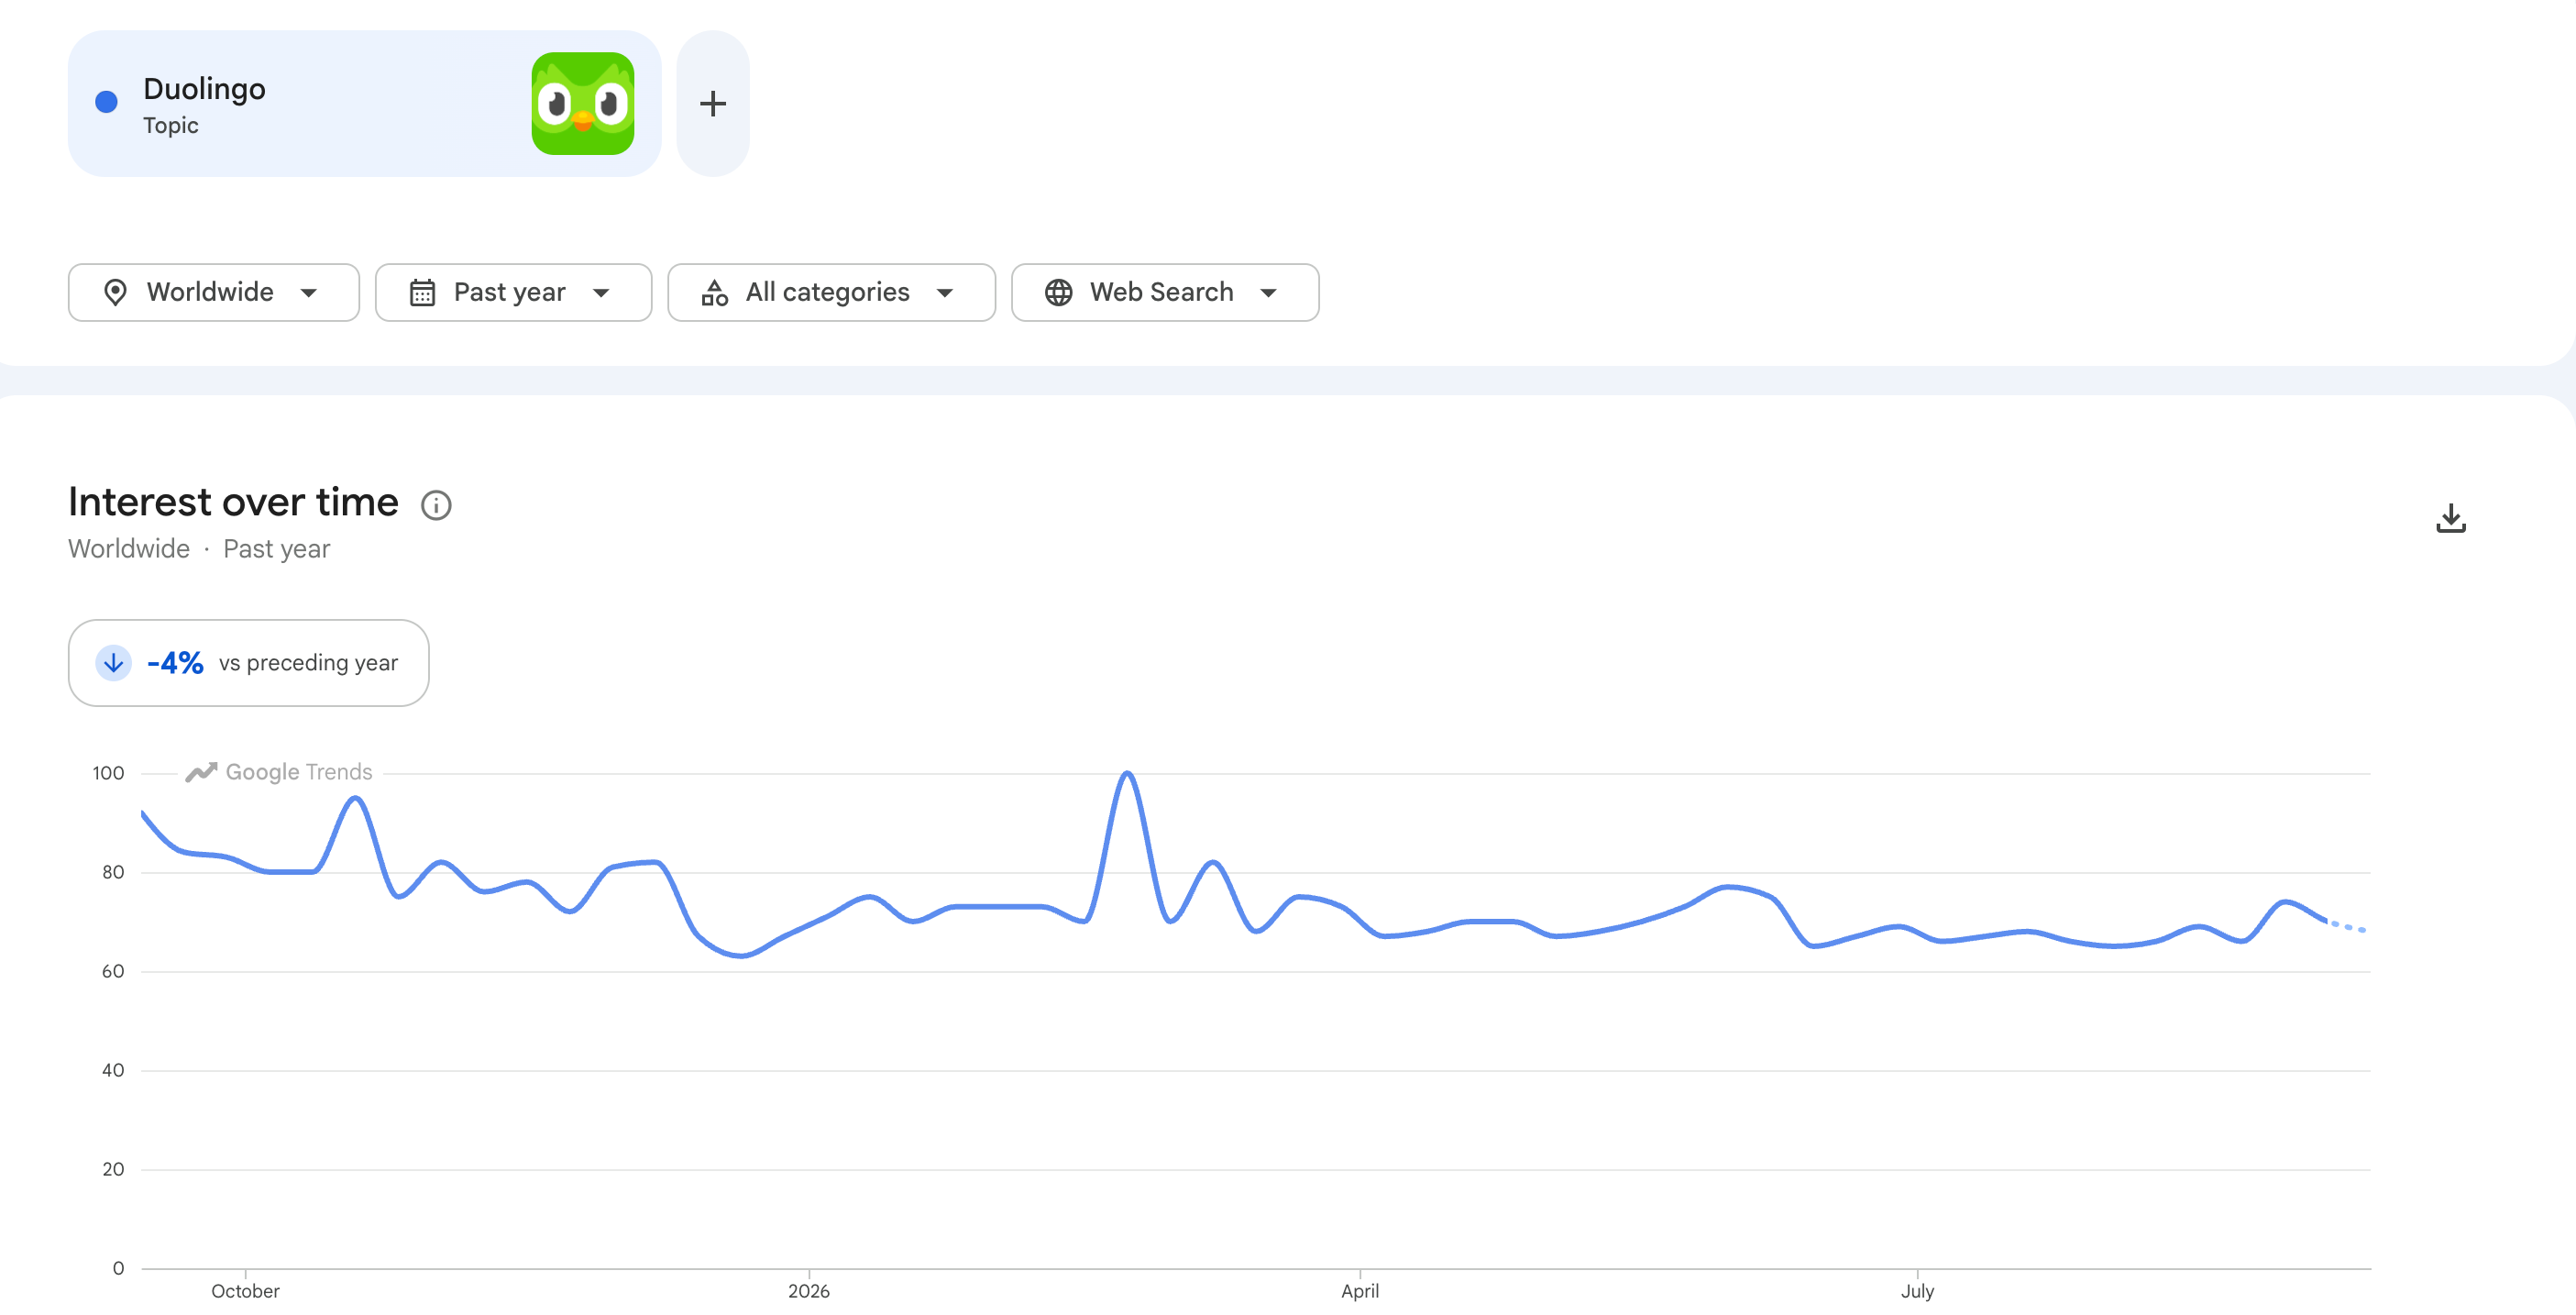
This is indeed confirmed by the interest over time, which over the past year only got worse.
You could argue that the recent DaU leaked on August 18 pointed to an acceleration to 27% YoY Growth, which confirms the reacceleration in bookings the management guided through the end of the year. Well, I am not surprised, because Duolingo is actually improving the product and farming the current user base, meaning that they are turning some MaU or inactive Users into DaU, and it is indeed working.
But new-user growth (measured with MaU growth as a proxy) has slowed a lot, which means they’ll hit a cap for the DaU, eventually (DaU is a subset of MaU).
In fact, looking at the sequential growth of MaU and DaU in the past, MaU led DaU all the way down from Q1 2023 to now, as it is logical to be, and it is still in a downtrend, with no sign of significantly reaccelerating.
Over the past year, we’ve built a stronger team and a more disciplined operating model, tripling both the number of channels in our mix and our performance creative output globally. We’re still early, but we’re already seeing this show up in top-of-funnel growth, and we’re increasingly confident that performance marketing can become a meaningful and efficient driver of long-term growth.
While they are clearly working on some levers, like performance marketing, I expected them to move much faster than this, experimenting with some game changing improvements like:
introducing multiplayer for language learning, to generate a network effect
introducing new courses beyond languages, math, music and chess, to increase the top of funnel surface
Duolingo has basically no competition now, and I think they are dissipating an important advantage which won’t last forever.
I am sure performance marketing as well as influencer-led marketing in China will bring results, but I am not any longer confident that this company has the potential to 10x in a few years, which is what I am looking for.
Of course, I may reconsider my thesis again as I get new inputs.
And here is how the DUOL stock performed from my initial deep dive on the January 11th 2025, when the price was $318.15, to when I closed the position on the July 24th 2026 at $122.10.
-62%If you want access to:
My portfolio
all my trades in real time
my price targets and how I calculate them
Business Ontology content
My price targets will be shared in the Telegram Group and explained on my Youtube channel.
Please note that:
I can be and will be (hopefully not often) WRONG. This is just my personal strategy—NOT FINANCIAL ADVICE. I don’t know your financial or life situation well enough to give any recommendations. Please do your own due diligence and research. Don’t be LAZY.
Be the architect of your own destiny.
Ciao
Lorenzo